
From risk to reputation: Jason Ho on what makes a bank worthy of trust

His view of banking is disarmingly simple: it is not a race for the biggest balance sheet or the fastest profit. It is a business built on trust – and on the discipline to protect that trust over time.
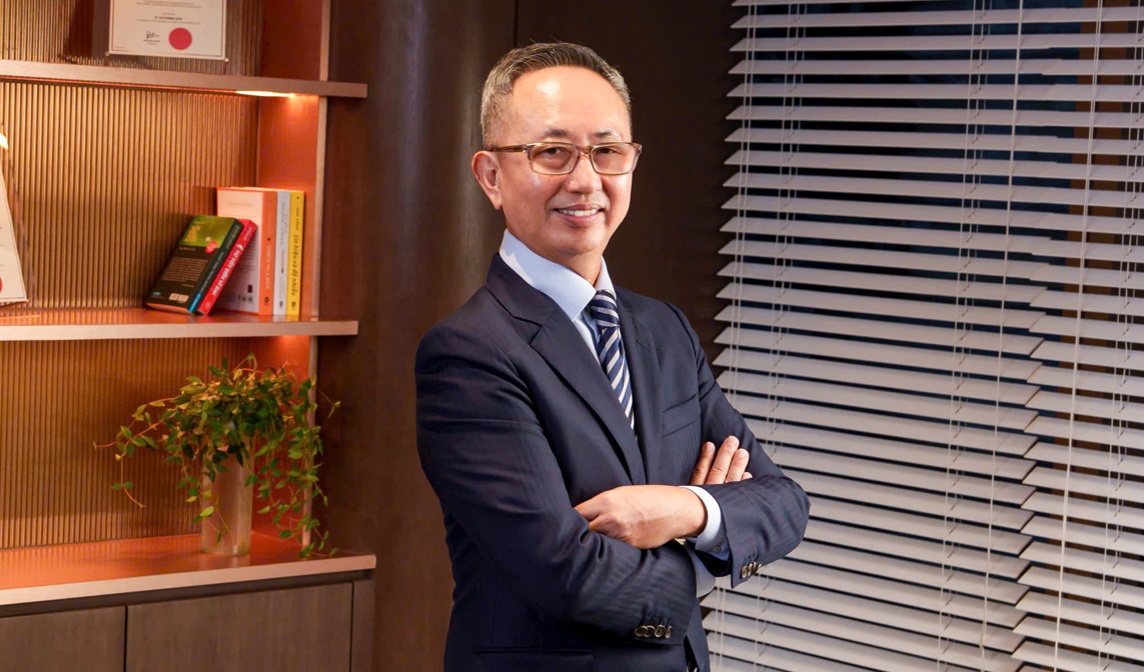
“Do what is right.” The phrase came up repeatedly during our conversation with Ho on an autumn day in Hanoi. Simple as it sounds, it captures a principle shaped by some of the most consequential moments of his career.
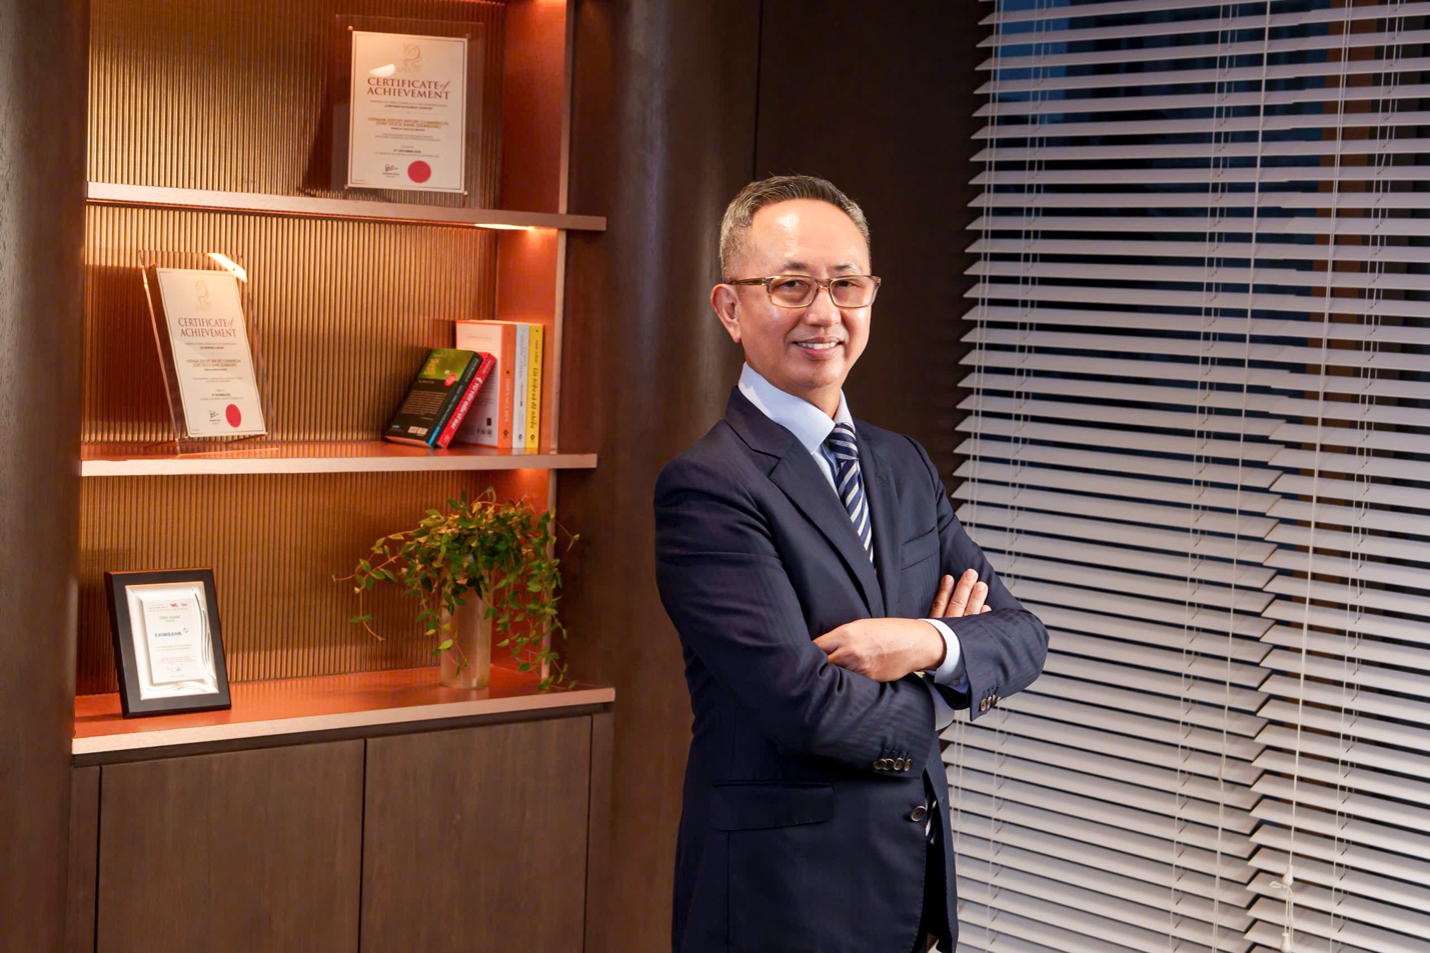 |
| Jason Ho, member of the Board of Directors at Eximbank, brings nearly four decades of banking experience. Photo: Eximbank |
For Ho, doing the right thing is not an abstract statement of values. It is a practical test of strategy: understanding what a bank is good at, knowing the risks it is prepared to take, and resisting opportunities that may look attractive today but undermine the institution five or ten years from now.
Lessons forged in crisis
Ho began his career in 1986 at Citibank, trading across foreign exchange, money markets, fixed income, and derivatives. He later moved to Volvo Group Treasury Asia, Standard Chartered, and KBC Bank, before joining OCBC, where he first led global asset and liability management and later became group chief human resources officer and a member of the bank’s senior management committees.
Two financial crises, however, did more than any job title to shape his philosophy of banking.
During the 1997 Asian financial crisis, Ho was corporate treasurer for Volvo in Asia-Pacific. He watched companies borrow US dollars at lower interest rates without fully appreciating the currency risk. When local currencies came under pressure, he spent weeks travelling across the region to manage the fallout. A decade later, the global financial crisis offered another lesson: institutions could report strong profits even as leverage, liquidity risk, and weak judgement were building beneath the surface.
The conclusion he drew from both episodes was not that banks should avoid risk. Risk is inherent in banking. The responsibility is to understand it, price it, manage it – and never lose sight of whose money and confidence are ultimately at stake.
“You are always tempted by money-making opportunities,” he said. “You have to ask whether a business fits the profile of the bank, what the implications are five or ten years from now, and whether these are risks you truly understand.”
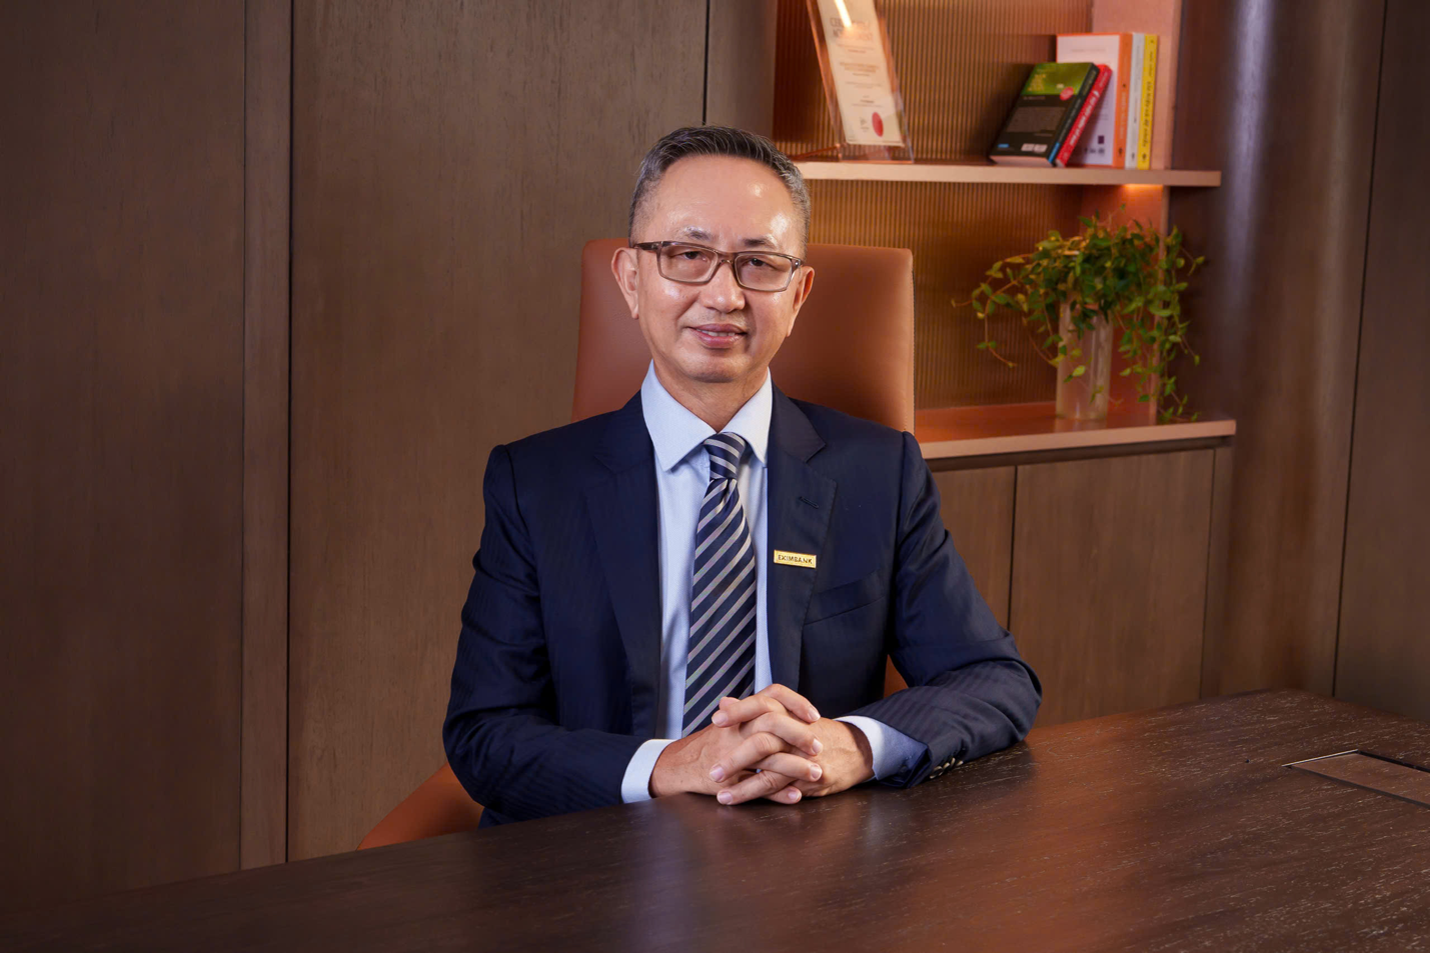 |
| Jason Ho shares his perspective on risk management and lessons shaped by financial crises. Photo: Eximbank |
Responsibility before returns
That perspective informs what Ho considers the foundations of a good bank: fiduciary responsibility, reputation, sound governance, and sustainable profitability. The order matters. Profit, in his view, is not the ultimate purpose of banking; it is an outcome when an institution consistently makes sound decisions, manages risk well, and earns the confidence of its customers.
“A good bank has an enormous responsibility towards its depositors, clients, employees, and shareholders,” he said. “Profitability is an outcome of the quality of what you have done.”
The point is personal for Ho. He grew up in a low-income family in Singapore and remembers his mother setting aside small amounts in the Post Office Savings Bank. That experience left him with a lasting appreciation of what even a modest deposit can mean to a household. Asked what a depositor should expect beyond interest rates, his answer is just three words: “peace of mind.”
Reputation is the other side of that promise. “It takes many years to build and can be destroyed in the blink of an eye,” Ho said. Once confidence disappears, even a financially sophisticated institution can find its room to manoeuvre narrowing rapidly.
This is why he returns repeatedly to governance. A strong corporate governance framework, he argues, creates the discipline for a bank to define responsibilities clearly, challenge assumptions, keep risk within agreed boundaries, and surface problems before they become crises.
For Ho, the board’s contribution is therefore distinct from management’s. Management executes strategy and runs the bank. The board provides oversight, approves strategy, oversees risk appetite, and asks difficult questions – while maintaining enough distance to exercise independent judgement. The relationship should be close enough for candid dialogue, but not so close that challenge disappears.
“The board should be close to the management team, but not too close,” he said. “Management executes and operates; the board provides oversight. We need a trusted partnership where management brings up not only the good news, but also the issues that are going off track.”
His career gives him a broad lens for that role. He has managed balance sheets and liquidity, worked through financial crises, led large-scale people transformation, and served on risk, ethics, digital, and sustainability committees. At Eximbank, he sees that experience as perspective for board discussions – not a mandate to run the bank.
“In banking, it is not about making money at all costs. It is about building a sustainable business that can grow in a meaningful way. If you do the right things - with the right people, culture, risk management and technology, supported by strong governance - sustainable profitability will follow.”
A long-term view of Eximbank
Ho joined Eximbank’s board in 2026 as the bank entered an important period of strategic review and transformation. He is careful about the distinction between governance and execution: his role is to contribute independent judgement, experience, and challenge at board level, while management remains accountable for operating the bank and delivering results.
That distinction also shapes how he thinks about success. Eximbank, he says, does not need to become the biggest bank in Vietnam. More important is whether it can build durable customer trust, strengthen its funding profile, keep risks under control, and create sustainable returns over time.
For the board, he favours a balanced scorecard rather than a single financial measure: sustainable return on equity growth, a stronger funding profile, customer satisfaction, employee engagement, fewer fraud incidents, and controlled NPLs. One telling culture measure, he suggests, is whether employees would recommend Eximbank as a place to work.
The same long-term lens applies to technology. Ho sees AI and digital investment as enablers, not ends in themselves: tools to understand customers better, improve decisions, and simplify experiences, while preserving human judgement where it matters.
What will change is the speed at which banks must adapt. Customer behaviour is evolving, and technology is reshaping expectations. “The core pillars won’t change,” he said. “But we must increase our ability to adapt and our learning agility.”
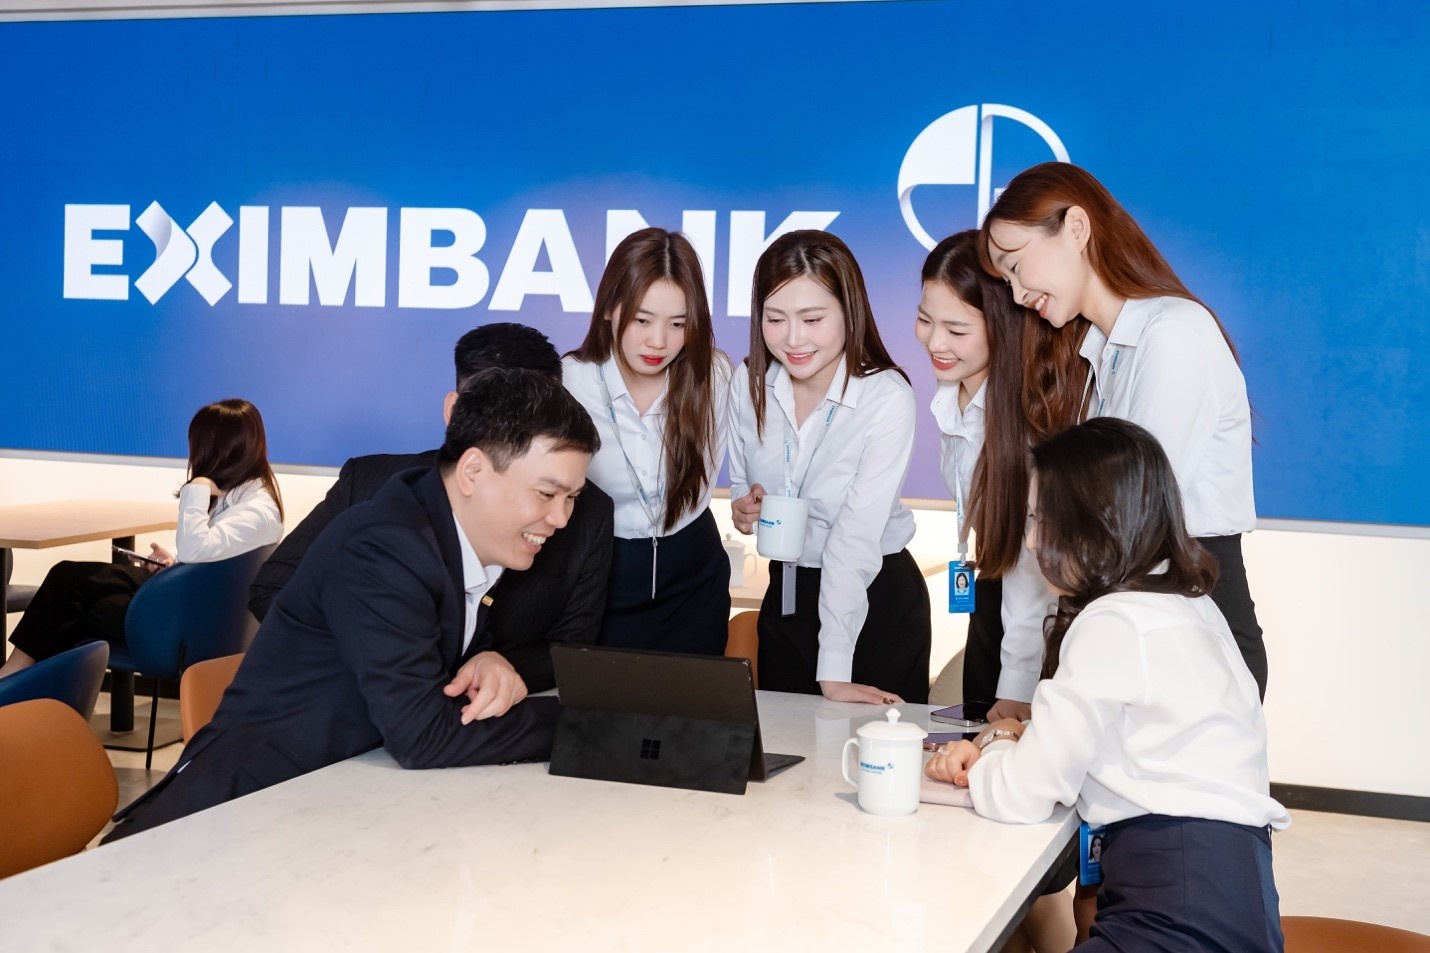 |
| Eximbank employees during a discussion, reflecting the role of people and culture in the bank’s transformation. Photo: Eximbank |
For customers, he wants that transformation to translate into something far less technical: peace of mind. For investors, the corresponding signals are governance, transparency, and institutional discipline.
Asked what depositors should expect beyond interest rates, Ho answered without hesitation, “Sleep at night knowing your deposits are safe. Trust that the bank will do the right thing. Simple, easy-to-use services. And fast, open support when problems arise.”
Eximbank is still early in that journey. The bank is examining customer journeys, where AI can improve service, and where human intervention remains important. For Ho, strategy, risk, culture, technology, management, and board oversight must reinforce one another rather than move in isolation.
At board level, an immediate priority is to ensure that Eximbank has a clear and comprehensive strategy for its next phase of development, with the board providing strategic direction and oversight, and management responsible for execution. Ho is realistic about the scale of the task. “We are moving fast,” he said. “If we get 70 per cent of it right over five years, Eximbank will be a very different bank.”
His ambition is not about size. “Eximbank doesn’t need to be the biggest,” he said. “We need to do things correctly.”
He also hopes to help develop a Young Banker Programme to build technical capability and the right values in a new generation – talent he sees as essential not only to Eximbank, but to Vietnam’s development as a credible financial centre.
 | Positive rate movement following government commitment Banks have taken swift action to reduce their deposit rates following a meeting with the central bank (SBV) on implementing measures to stabilise deposit rates on February 25. |
 | Eximbank advances corporate governance and leadership roadmap Eximbank on August 1 announced the next milestone in its 2026-2030 Development Strategy, continuing the enhancement of its corporate governance framework and executive leadership structure. |
 | Vietnam’s consumer finance market shifts from expansion to sustainable quality Vietnam's consumer finance market is entering a new phase, with the focus shifting from scale to the quality of growth. Oanh Tran, senior manager of Market Research & Consulting Services at FiinGroup, spoked with VIR’s Thanh Van about the changes in the competitive landscape. |
What the stars mean:
★ Poor ★ ★ Promising ★★★ Good ★★★★ Very good ★★★★★ Exceptional
 Tag:
Related Contents
Latest News
More News
- Policy loans open new paths for people rebuilding their lives (October 07, 2026 | 17:24)
- FTSE upgrade opens door to $2 billion in passive fund inflows (October 07, 2026 | 12:12)
- VIB raises $1 billion from international markets in record funding plan (October 07, 2026 | 10:28)
- From loans to women’s economic empowerment (October 06, 2026 | 17:58)
- VIB named Outstanding Retail Bank 2026, targets transaction banking (October 06, 2026 | 10:52)
- FTSE upgrade paves way for stronger stock market development (October 05, 2026 | 18:44)
- coLoan to empower women through inclusive green finance (October 05, 2026 | 18:42)
- Techcombank CEO: AI no longer a tool but a new operating foundation (October 05, 2026 | 18:11)
- Banks sustain profit growth as funding costs squeeze margins (October 02, 2026 | 22:22)
- Nam A Bank delivers strong breakthrough in 2026 (October 02, 2026 | 19:00)
 Mobile Version