

New credit push aims to widen SME access to capital

In an interview with VIR on September 22, a FiinGroup representative said only 20.5 per cent of small- and medium-sized enterprises (SMEs) currently have outstanding bank loans. The gap is even wider across business sizes, with just 8.8 per cent of micro enterprises accessing bank credit, compared with 61.4 per cent of large enterprises, nearly seven times higher.
Even among businesses that have been operating for more than five years and are classified as medium- or low-risk, more than 40 per cent have never accessed bank credit. In the trade sector, which has the largest concentration of SMEs, an estimated 70,000 low-risk businesses have yet to secure bank loans.
According to the State Bank of Vietnam (SBV), as of September 18, 19 commercial banks had registered to participate in the programme, with a total credit scale of around $16.28 billion. Loans under the programme carry interest rates at least 1 percentage point per year below the lending rates applied by each participating bank to loans of the same tenor.
“Credit remains one of the essential resources enabling businesses to maintain, recover, and expand their operations. Therefore, the banking sector has implemented a range of coordinated measures to facilitate SMEs’ access to capital,” said Nguyen Ngoc Canh, Deputy Governor of the SBV. “But we also need to acknowledge frankly that SMEs still face problems in accessing capital that need to be addressed. A bank may have funding available, but lending decisions still have to be based on its ability to assess risk and the borrower’s capacity to repay. Meanwhile, many SMEs face limitations in financial data, corporate governance, collateral or their ability to develop sufficiently convincing business plans. Therefore, if banks are simply asked to open the credit tap without changing how information is generated, shared, and used, the bottleneck may remain.”
In practice, however, SMEs still have to pass through multiple doors when seeking financing. Each bank has its own procedures, forms, assessment criteria, and documentation requirements, forcing businesses to prepare, supplement, and explain similar information repeatedly.
Nguyen Thanh Nghi, CEO of Thien Minh Rating (TMR), pointed to a broader issue behind this administrative burden: information asymmetry.
“Banks need to know whether a business can generate sufficient cash flow and repay its debt, but they do not always have access to sufficiently standardised, transparent, and reliable information to make that assessment quickly. Conversely, a business may have sound operations but still have to spend considerable time proving its financial strength to each individual bank,” he said. “When the due diligence process is prolonged, costs rise for both sides. For businesses, delayed access to capital can mean missing an order, a contract or an opportunity to expand production. Against this backdrop, TMR has proposed digitising and standardising corporate documentation, incorporating independent credit-rating results to create a digital passport.”
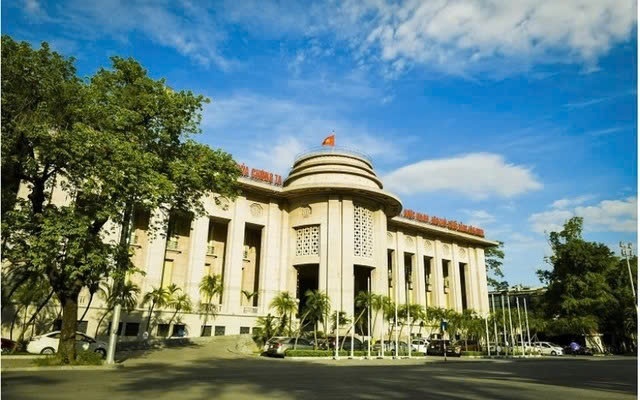 |
| Photo: SBV |
Nghi said the approach goes beyond simply replacing paper documents with electronic files, instead seeking to create a comprehensive and standardised information package supplemented by an independent assessment of a company’s creditworthiness. When working with banks, businesses could use this package rather than starting the process from scratch each time, while banks would gain an additional independent reference point in their risk assessments.
“If widely adopted, this could become a common language between businesses and capital providers, helping shorten the due diligence process and reduce transaction costs,” he said. “More broadly, the value of a digital passport lies not in the technology itself, but in the quality of the information behind it. TMR is focusing on three areas: helping businesses digitise their corporate profiles; advising them on standardising their documentation and financial management; and providing independent risk assessments to create an objective and transparent reference point for both businesses and banks.”
From a policy perspective, the TMR representative proposed that the SBV allow or encourage banks to pilot the use of digital corporate profiles combined with independent credit ratings when assessing credit applications.
Nghi also called on regulatory authorities, particularly the Ministry of Finance, to study mechanisms for managing and sharing data between credit institutions and licensed independent credit-rating agencies.
“Data connectivity, if implemented in accordance with regulations, could make credit assessments faster and more efficient,” he said. “But for the market to establish a new standard, the responsibility does not rest solely with banks or regulators. Businesses also need to rethink how they manage and provide information. A company with standardised financial records, reliable data and independently verified creditworthiness will have a stronger basis for demonstrating its capacity when seeking capital.”
 | SBV credit policy shift puts banks and developers in spotlight The State Bank of Vietnam's easing of capital rules and special credit treatment for strategic projects is expected to expand lending capacity, with banks, property developers and infrastructure companies emerging as the biggest beneficiaries. |
 | SBV excludes tourism and resort loans from real estate credit growth The State Bank of Vietnam has issued Official Letter No.8509/NHNN-CSTT to 25 credit institutions, adjusting the calculation of certain loan balances when controlling real estate credit growth in 2026. |
What the stars mean:
★ Poor ★ ★ Promising ★★★ Good ★★★★ Very good ★★★★★ Exceptional
 Tag:
Related Contents



Latest News
More News
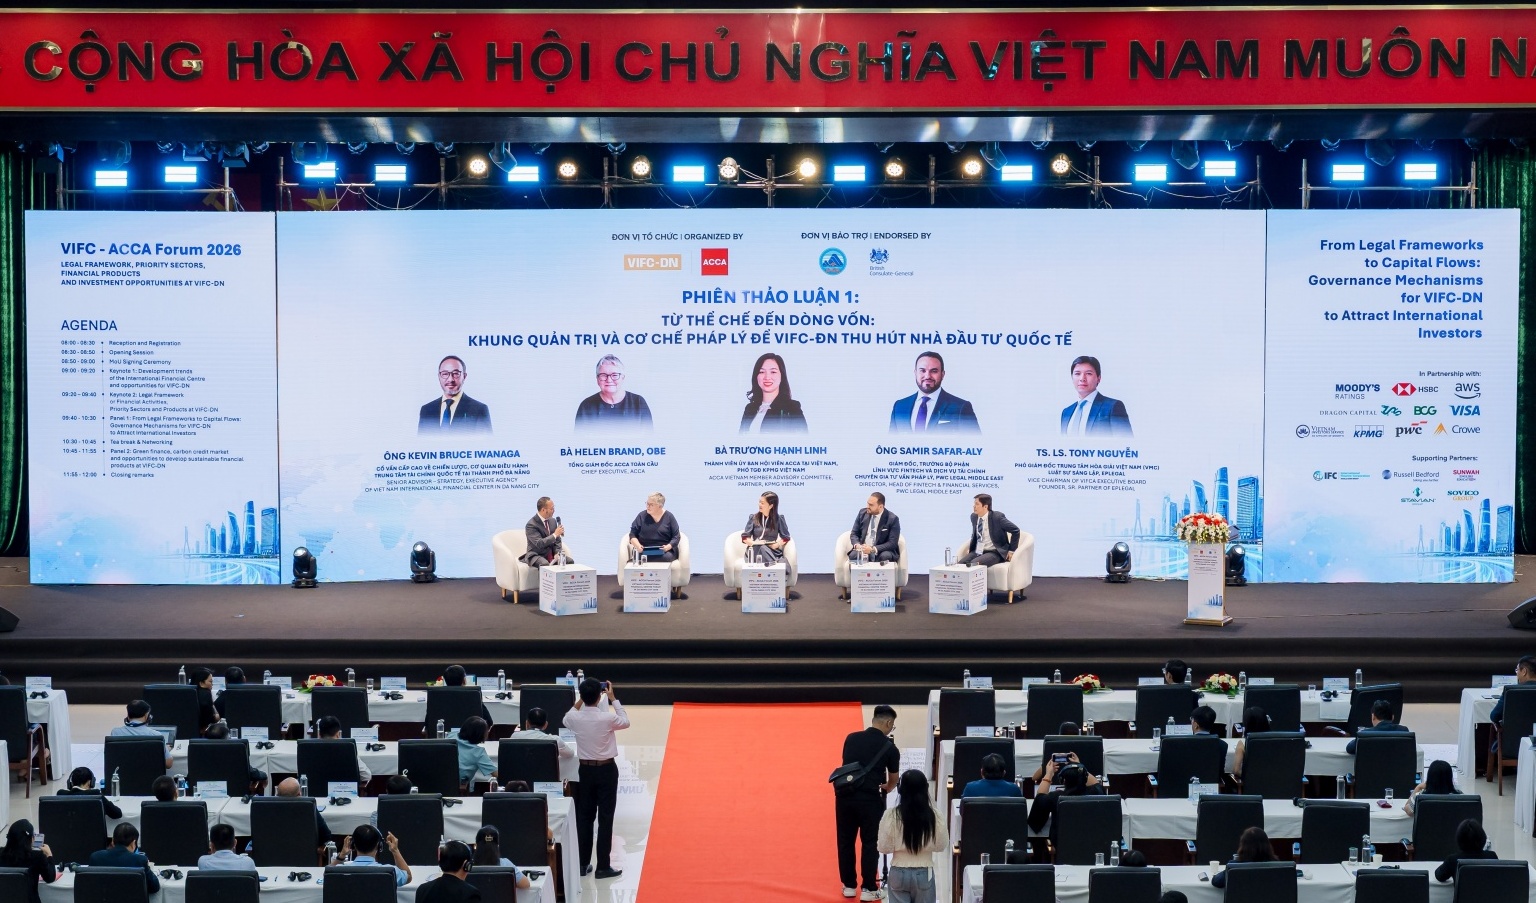
- VIFC-Danang forum focuses on green finance and regulatory certainty (September 23, 2026 | 17:48)
- VIFC steps up focus on talent and green finance (September 23, 2026 | 17:34)
- Fundiin and TNEX forge strategic partnership for personalised digital finance (September 23, 2026 | 17:32)
- Fund industry must strengthen institutional investor base: SSC (September 22, 2026 | 15:40)
- Fund industry needs broader investor base to reach growth goals (September 22, 2026 | 15:30)
- Awards seek benchmark for investment funds (September 22, 2026 | 15:00)
- VIFC-HCMC and ACCA prioritise global-standard finance talent (September 22, 2026 | 11:00)
- Green finance, carbon markets emerge as key focus for Danang's VIFC (September 22, 2026 | 10:00)
- How policy loans help STEM students build their future (September 21, 2026 | 16:19)
- Vietnam congratulated as an emerging market (September 21, 2026 | 16:14)


 Mobile Version